How to Stop Impulse Spending: A Behavioral Reset for 2026
Impulse spending is fast. It’s reflexive. It’s “I didn’t plan this, but it’s in my cart now.” Emotional spending is mood-driven.
 FIYR
Impulse spending is fast. It’s reflexive. It’s “I didn’t plan this, but it’s in my cart now.” Emotional spending is mood-driven.
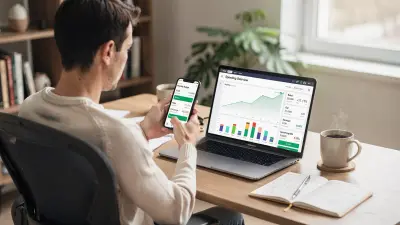
Most budgets don’t fail because you’re “bad with money.” Spending rules automation fixes that. It’s not sexy. It’s not a side hustle.
Your net worth is a scoreboard. Liabilities are the points your opponent scored while you were busy high-fiving yourself for having a savings account.
Most personal budgets in 2026 are still run with 1990s software habits, and it shows. Meet Alex, a longtime Quicken loyalist.
Raises are celebrated, then quarantined. They keep categories capped, lock in housing and transportation for longer, and upgrade with rules, not vibes.
Most people think retiring early is about finding a hot stock or striking it rich with a side hustle. Cute. The real unlock is a boring fraction.
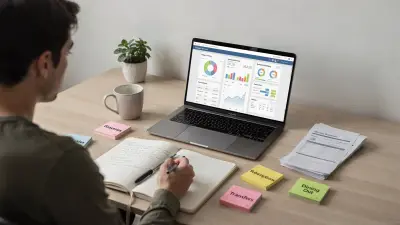
Most budgets fail for a simple reason, the humans in charge get tired. A budgeting rule is an if-then instruction that runs when a transaction arrives.
Most people swear off credit cards because they think plastic wrecks budgets. Wrong villain. The real budget killer is messy tracking.
Quotable: Your budget should not swing like a crypto chart every time soccer season starts. No shame, just systems. Give this 30 days.