Budgeting in Your 20s When Adulthood Gets Expensive
Budgeting in your 20s is uniquely chaotic because your income and your expenses are both changing at the same time.
 FIYR
Budgeting in your 20s is uniquely chaotic because your income and your expenses are both changing at the same time.
Most people do not have a net worth tracking problem. They have a data hygiene problem wearing a Patagonia vest and calling itself a dashboard.
Daily tracking feels responsible. It has that productive little dopamine hit, like closing browser tabs or buying a planner you will abandon by February.
If you’re trying to budget in 2026 without a system, congratulations, you are basically raw-dogging modern capitalism.
Sarah sets up an auto-transfer: $400 to savings on payday. She feels financially responsible and slightly superior. Then day 9 happens.
Let’s call him Jake. Jake makes decent money. He reads finance threads. He knows what a Roth IRA is (and actually has one).
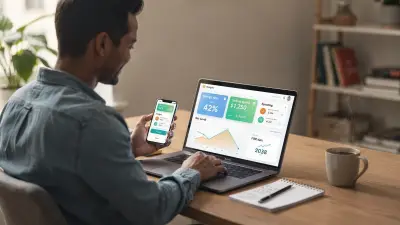
Jake is a competent adult. W-2 job. Pays rent. Has a 401(k). Uses a generic budgeting tool that makes adorable pie charts.
Your budget has been lying to you. Not in a “the government is tracking your latte” way. In a much more annoying way.
If your money tracker makes you feel like a detective, a data janitor, and a part-time accountant, congratulations, you bought the wrong tool.