Why a FIRE-Focused Budgeting App Beats Generic Budgets
Generic budgets have one fatal flaw: they treat your money like it exists in a vacuum.
They’ll tell you that you spent $312 on “Food & Dining” (cool), but they won’t tell you what that did to your freedom timeline (the part that actually matters). It’s like stepping on a scale without having a goal. Informative, sure. Useful, maybe. Motivating, almost never.
Meanwhile, the stakes are not cute. According to CNBC, about 60% of Americans say they’re living paycheck to paycheck, and a big chunk are stressed about money and carrying credit card debt (CNBC). If your “budget” doesn’t actively help you break that cycle, it’s not a budget, it’s a spreadsheet cosplay.
A FIRE-focused budgeting app beats generic budgets because it connects today’s spending to tomorrow’s optionality. Not just “how did I do this month?” but “how fast am I buying my freedom?”
Here’s the part nobody talks about: FIRE isn’t a motivation problem. It’s a measurement problem.
The real reason generic budgets underperform
Let’s meet Jake.
Jake is a competent adult. W-2 job. Pays rent. Has a 401(k). Uses a generic budgeting tool that makes adorable pie charts. Jake also has a recurring $19.99 subscription for a meditation app he stopped using in 2022, because “canceling is annoying.”
Jake’s budget says he’s “fine.” Jake’s bank account says he’s “fine.” Jake’s stress level says otherwise.
Because generic budgets usually fail in four predictable ways:
1) They optimize the wrong outcome
Generic budgets optimize for “not overspending” (vibes) instead of financial independence (math).
For FIRE, the key question is not “Did I stay under $200 for restaurants?”
It’s:
- What is my actual burn rate?
- What is my savings rate?
- How does this month change my projected FIRE date?
If your tool can’t answer those, it’s like training for a marathon using only a Fitbit step count.
Quotable truth: A generic budget measures activity. A FIRE budget measures progress.
2) They ignore the scoreboard that drives FIRE
FIRE is basically a game with a small set of stats:
- Spending (your burn rate)
- Savings rate
- Net worth
- Liabilities and debt drag
- Time (your runway and your timeline)
Generic budgeting tools often stop at “spending by category.” Which is like watching the first 10 minutes of a movie and guessing the ending.
3) They make “savings” a fuzzy afterthought
Most people save whatever’s left over. That’s adorable. It’s also why they stay broke.
FIRE flips the order: save first, spend what’s safe. That requires a system that can track savings accurately and show you a realistic “safe-to-spend” number based on your real cash flow.
4) They don’t handle modern money chaos
Your money life in 2026 is not a clean, consistent routine. It’s:
- subscriptions multiplying like gremlins
- irregular income (bonuses, freelance, side gigs)
- lumpy “true expenses” (insurance, repairs, annual renewals)
- credit cards, refunds, transfers, BNPL
Generic budgets weren’t built for this. They were built for a world where you wrote checks and people clipped coupons. Respectfully, that world is dead.
What a FIRE-focused budgeting app does differently (and why it works)
A FIRE-focused budgeting app is built around the question: How do I turn cash flow into freedom faster, without hating my life?
That sounds dramatic. It’s also the correct question.
Here’s what changes when your budget is FIRE-first.
It ties spending to a timeline
FIRE is a timeline sport.
Spending less is good, sure. But what’s better is knowing the payoff:
- Cutting $300/month is not just “nice.”
- It can reduce your FI target (because your spending is lower).
- And it can increase your investable surplus.
That is a double win, and it’s why FIRE people love obsessing over burn rate.
If you want the math in plain English, FI is usually estimated with the “Rule of 25” (annual spending x 25) as a starting point, based on the classic 4% rule research.
A FIRE-focused system keeps this grounded in reality, because it’s driven by your actual transactions, not your optimistic self-image.
It makes savings rate the main event
Your savings rate is the closest thing personal finance has to a cheat code. It’s also the easiest number to lie to yourself about.
A FIRE tool should calculate and track savings rate consistently, using real income and real expenses, so you can spot trends and fix leaks.
If you want the deeper playbook, see: Savings Rate for FIRE: The Fastest Path to Freedom.
It treats net worth like a living dashboard, not a once-a-year shame ritual
Net worth is not your self-worth, but it is your optionality score.
A FIRE-focused budgeting app should track:
- assets
- liabilities
- the trend
…and help you connect day-to-day spending decisions to that long-term picture.
If you’re newer to this, start here: How to Calculate Net Worth: A Simple Guide With Examples.
It respects the two villains of FIRE progress: subscriptions and true expenses
Two things quietly murder budgets:
- recurring subscriptions you forgot about
- irregular, predictable bills you didn’t plan for (car repairs, annual fees, insurance)
A FIRE-focused system calls those out and makes them visible, because “random” expenses aren’t random. They’re just unlabeled.
If you want the fastest cleanup routine, see: Reduce Subscriptions in 2026: A 30-Minute Cleanup Plan.
Generic budget vs FIRE-focused budgeting app (quick reality check)
| What you need | Generic budget usually gives you | A FIRE-focused budgeting app gives you |
|---|---|---|
| A decision you can make today | Category totals and charts | A clear safe-to-spend signal and budget caps that match reality |
| Motivation that lasts past Day 9 | “Be disciplined” energy | Timeline feedback (your FIRE date moves when your behavior moves) |
| A way to stop invisible spending | Manual audits, maybe | Subscription tracking plus rules to keep recurring charges labeled |
| Long-term context | Maybe a net worth tab, if you dig | Net worth + liabilities + savings rate as a unified scoreboard |
| Automation | Some basic categorization | Custom categories and transaction rules that keep data clean over time |
| FIRE planning | Not really | FIRE projections based on your real spending and savings |
Quotable truth: Generic budgets tell you what happened. FIRE budgets tell you what it means.
The FIRE Money Scoreboard (the only metrics that really matter)
If your system doesn’t surface these numbers, you’re driving with the windshield covered and bragging about your stereo.
1) Monthly burn rate
This is your real monthly spending, ideally averaged over the last 3 to 12 months.
Why it matters: burn rate drives your FI number.
2) Savings rate
The simple version:
- Savings rate = (Income − Expenses) ÷ Income
Why it matters: savings rate drives speed.
3) Net worth trend
Net worth is a movie, not a photo.
Why it matters: the direction tells you if your system is working.
4) Subscription load
Not just “how many,” but total monthly cost.
Why it matters: subscriptions are the modern tax you volunteered for.
5) Safe-to-spend
This is the weekly or monthly number you can spend without blowing your plan.
Why it matters: it turns budgeting from restriction into permission.
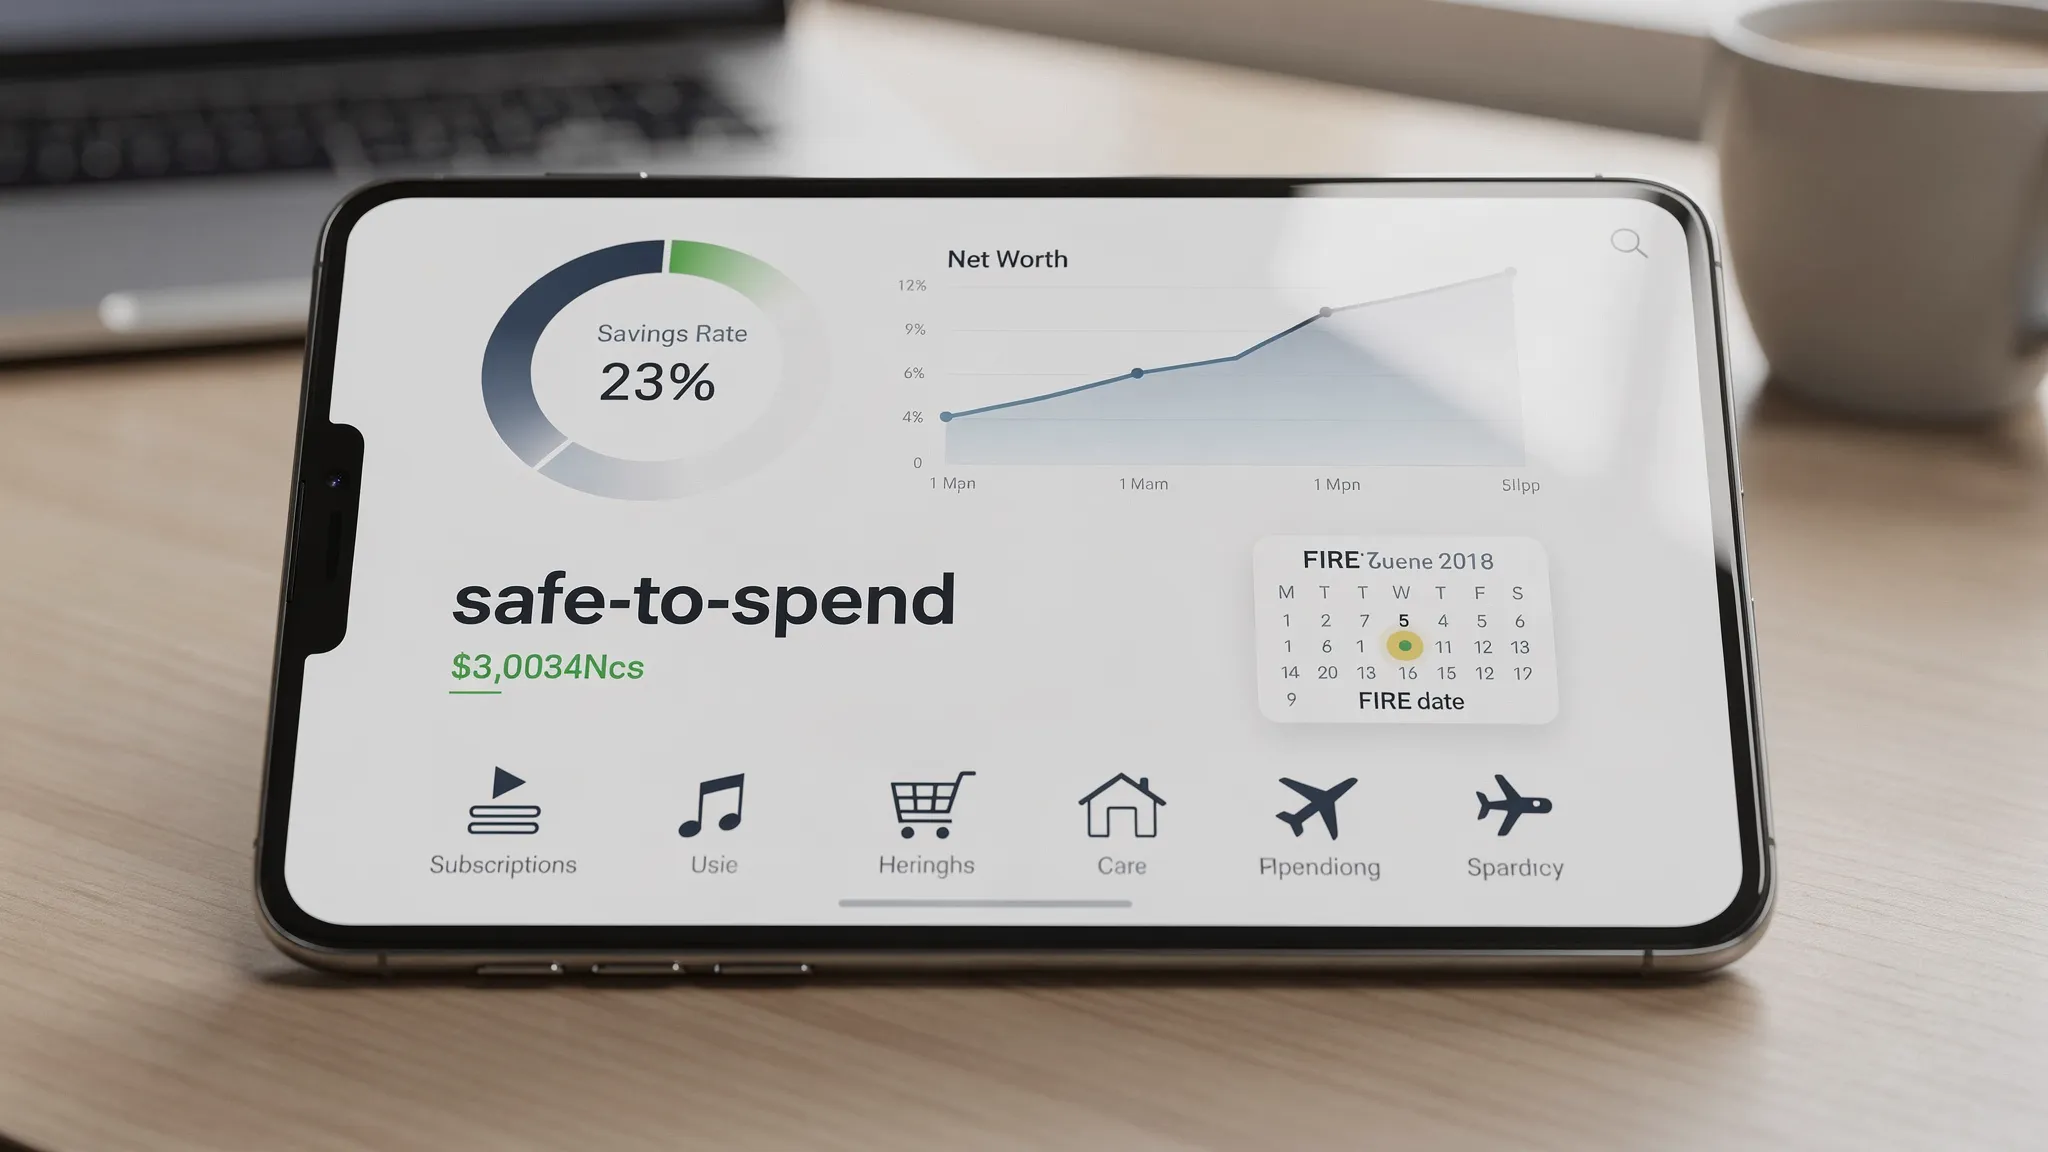
FIYR is built around this kind of scoreboard: tracking income, expenses, subscriptions, net worth (assets + liabilities), savings rate, and FIRE projections in one place. Less tab-switching, more truth.
The “FIRE-First Budget” setup (45 minutes, no spreadsheets harmed)
You don’t need a perfect budget. You need a budget that survives your worst week.
Here’s a clean setup you can do in one sitting.
Step 1: Build three buckets that map to FIRE
This is the simplest structure that actually works:
- Floor: must-pay essentials (housing, utilities, groceries, minimum debt payments)
- Flex: lifestyle spending that fluctuates (dining, fun, shopping)
- Future You: investing, savings goals, sinking funds, extra debt payoff
This is how you turn budgeting into an operating system instead of a monthly argument with yourself.
Step 2: Create 8 to 12 decision-focused categories
Most budgets die because of category chaos.
Use categories that drive decisions. Examples:
- Groceries
- Convenience Food
- Restaurants
- Transportation
- Subscriptions
- Travel
- Health
- Home and Maintenance
- Fees and Interest
If you want to go deeper (and cleaner), use custom categories and category groups so you can answer questions like “How much did Amazon cost me this month, and was it needs or wants?”
FIYR supports custom categories and category groups, so you’re not stuck with “Shopping” as your financial personality.
Step 3: Add a “Stuff I Forgot” buffer (because you will forget stuff)
Pick a small monthly buffer category. Call it:
- Stuff I Forgot
- Chaos Tax
- Human Error
Whatever makes you laugh while you’re being financially responsible.
Step 4: Automate the boring parts with transaction rules
Rules are how you stay consistent without becoming a full-time accountant.
A starter set:
- Auto-tag recurring bills (rent, insurance)
- Catch subscriptions (anything monthly with the same merchant)
- Normalize messy merchants (Amazon, Target, Apple)
FIYR includes automatic transaction rules, which is basically the closest thing to “set it and forget it” that personal finance allows.
Step 5: Track net worth monthly (10 minutes)
Once a month, update what needs updating. The goal is not perfection, it’s trend accuracy.
If you want the ritual: Monthly Net Worth Tracking: The 10-Minute Ritual That Works.
Step 6: Install a weekly 12-minute money check-in
This is the habit that turns “I should” into “I did.”
Weekly agenda:
- Check safe-to-spend
- Scan top 5 merchants
- Fix any miscategorized transactions
- Look at savings rate trend
- Pick one lever for next week (one, not twelve)
Quotable truth: Your budget doesn’t need more discipline. It needs a meeting invite.
A quick story: how FIRE budgeting changes behavior
Meet Sarah.
Sarah is not reckless. Sarah is just busy. Two kids, job, and a phone that offers one-click dopamine delivery.
She switches from a generic budget to a FIRE-first setup and discovers two things in week one:
- Her “small subscriptions” are a real monthly bill.
- Her “random expenses” are mostly predictable, she just wasn’t smoothing them.
She sets a subscription cap, adds a few sinking funds, and starts watching savings rate like it’s a sports score.
Nothing magical happens. No guru appears. No one yells “cut lattes.”
But her savings rate creeps up, her safe-to-spend stops surprising her, and her FIRE projection starts moving in the right direction.
The win is not deprivation. The win is control.
How to choose the right FIRE-focused budgeting app (non-negotiables)
If you’re shopping for a FIRE-focused budgeting app, here’s what to demand.
- Accurate income and expense tracking (with clean charts and drill-down)
- Custom categories (because your life is not a default template)
- Transaction rules (because manual categorization is a slow death)
- Subscription tracking (because recurring charges are stealth spending)
- Net worth tracking (assets + liabilities, not just balances)
- Savings rate calculation (consistent, transparent)
- FIRE projections (so the budget connects to an actual goal)
- Goal tracking and safe-to-spend (so you know what you can spend without regret)
FIYR is designed around exactly this blend: flexible budgeting and money tracking, plus FIRE-focused insights like a FIRE date calculator driven by your real data.
Frequently Asked Questions
What is a FIRE-focused budgeting app? A FIRE-focused budgeting app is built to connect day-to-day spending to FIRE metrics like savings rate, net worth, and a projected financial independence timeline, not just category totals.
Do I need a FIRE-focused app if I’m not trying to retire early? Not at all. But if you want more options (career flexibility, sabbaticals, less stress), FIRE-style tracking is still useful because it focuses on savings rate, runway, and net worth momentum.
Can I do FIRE with a generic budget and a spreadsheet? Yes, if you enjoy maintaining spreadsheets and you’re consistent. Most people are not consistent. The advantage of a FIRE-focused app is automation, cleaner data, and faster feedback loops.
What’s the single most important FIRE metric to track weekly? Savings rate, because it’s the bridge between your daily decisions and your long-term freedom. Pair it with safe-to-spend so you can act on it in real life.
How does subscription tracking help with FIRE? Subscriptions increase your monthly burn rate, which increases your FI number. Cutting or capping subscriptions lowers your burn, increases surplus, and usually improves your FIRE timeline without touching the big joys in your life.
Want your budget to do more than shame you once a month?
If you’re pursuing FIRE, you don’t need another generic budget that politely reports the damage after it’s done. You need a system that tracks the truth, automates the boring stuff, and shows you the one thing you actually care about: progress.
FIYR is a modern personal finance platform built for that. It helps you track spending and income, create flexible budgets with a safe-to-spend signal, automate categorization with rules, monitor subscriptions, track net worth (assets and liabilities), and project your FIRE timeline using your real numbers.
Get your money system out of the stone age and into “I know exactly what I’m doing.” Learn more at FIYR’s blog.