FIYR Money Tracker Review: Clean Data, Clear Decisions
If your money tracker makes you feel like a detective, a data janitor, and a part-time accountant, congratulations, you bought the wrong tool.
Most people don’t “overspend” because they’re reckless. They overspend because the numbers lie, the categories are mush, and the system is allergic to real life.
Meanwhile, 60% of Americans are living paycheck to paycheck (which is a fancy way of saying “one car repair away from chaos”). That’s not a willpower problem. That’s a visibility problem. Source: CNBC.
This is a FIYR money tracker review for people who want clean data and clear decisions, not another pastel dashboard that politely ignores your DoorDash habit.
What FIYR is (and what it’s not)
FIYR is a modern personal finance platform built for people who want control of the basics (income, expenses, budgets, subscriptions) and the big picture (net worth, savings rate, and a FIRE timeline).
It positions itself as a modern alternative to Mint, Monarch Money, Copilot, Rocket Money, and Quicken, with a heavy emphasis on:
- Clean transaction data you can trust
- Flexible budgeting that survives real life
- Automation (transaction rules, categorization)
- FIRE-focused metrics (savings rate + projected FI/FIRE date)
What it’s not: a magical wand that fixes a broken money life without you looking at your money. The app can do a lot, but you still have to show up. (Briefly. Like 10 minutes a week. You can keep your dignity.)
The core promise: clean data, clear decisions
A good money tracker does two jobs:
- Tell the truth about what happened.
- Tell you what to do next without requiring a PhD in spreadsheet coping mechanisms.
FIYR’s approach is pretty aligned with that philosophy: track everything, keep categories meaningful, automate the repetitive stuff, and surface the metrics that actually move your life.
Here’s the part nobody talks about: most finance apps fail at step one. If your data is messy, every decision downstream is a guess wearing a blazer.
The FIYR review scorecard (what matters in 2026)
Instead of “wow, nice charts,” here’s a more useful way to evaluate a tracker: whether it reduces financial confusion.
| What you need from a tracker | What FIYR supports | Why it matters in real life |
|---|---|---|
| Accurate spending and income tracking | Income and expense tracking, full money tracker | You cannot out-hustle bad data. |
| Budgets that don’t collapse on contact | Dynamic budget options, flexible budgeting | Rigid budgets are cute until your fridge dies. |
| Categories that mean something | Custom categories and category groups | “Shopping” is not insight, it’s a shrug. |
| Less manual work | Automatic transaction rules | Consistency beats motivation every time. |
| Subscription visibility | Subscription tracking | Recurring charges are stealth spending with a subscription logo. |
| Net worth clarity | Assets + liabilities tracking | Net worth is your financial gravity, ignore it and you pay for it. |
| FIRE progress you can actually measure | Savings rate calculator + FIRE date calculator | FIRE is math, not vibes. |
| Goal clarity | Goal tracking + safe-to-spend balance | Your goals need a lane, not a wish. |
If you like the idea of that stack, FIYR is in the right neighborhood.
A quick story: the “Mint refugee” spiral
Meet Josh. (Not a real Josh, but spiritually, definitely Josh.)
Josh used Mint for years. Then Mint went away, and he tried a new app. It looked slick. It also shoved 30 categories in his face and categorized every Target run as “Shopping,” including groceries, diapers, and a sad overpriced extension cord.
So Josh did what any self-respecting adult does when confronted with mild inconvenience.
He stopped checking.
Three months later, he’s confused why his savings didn’t grow, annoyed at himself, and somehow paying for two streaming services he swore he cancelled.
This is where FIYR tends to win: it’s designed to make the “checking in” part survivable.
Hands-on: how FIYR feels for actual humans
1) Money tracking that doesn’t punish you for being busy
FIYR is built around a simple idea: track the truth first, then build guardrails.
When your tracker is doing its job, you can answer:
- “Where did the money go?”
- “What’s safe to spend this week?”
- “What do I need to change next month?”
Without opening 17 tabs and negotiating with your own denial.
2) Categories and groups: the difference between insight and noise
FIYR supports custom categories and category groups, which is the unsexy superpower most people only appreciate after years of “Misc” shame.
The point is not to build a museum of spending. The point is to build categories that create decisions.
A clean pattern that works for most people:
- Keep 8 to 12 core categories
- Add a few “high-leverage” custom categories (the ones that actually move your budget)
- Use rules to keep them consistent
If you want a deeper category framework, FIYR’s blog has a solid companion piece: Budgeting categories list: a clean setup that works.
Quotable truth: If your categories don’t change your behavior, they’re just decorative.
3) Transaction rules: automation that makes your budget less fragile
Manual categorization is where good budgets go to die.
FIYR includes automatic transaction rules, which are basically “if this, then that” logic for your money. The goal is simple: make your data cleaner over time with less effort.
A practical starter kit of rules most people should set up:
- Lock recurring bills to the right categories
- Fix your top 5 merchants (Amazon, Target, Costco, your main grocery store, your favorite “just one coffee” place)
- Route weird stuff into a “Needs Review” category
If rules are your love language, go deeper here: Automated budgeting: how rules save time and keep your spending accurate.
One-liner: Automation is how you budget like a robot without becoming one.
4) Subscription tracking: the stealth tax you can actually fight
Subscriptions are the easiest money leak because they are:
- Small enough to ignore
- Frequent enough to add up
- Automatic enough to feel invisible
FIYR’s subscription tracking is valuable because it ties recurring charges back to the rest of your system, not just a cancellation list.
If you want a fast cleanup method, pair the tracker with this: Reduce subscriptions in 2026: a 30-minute cleanup plan.
Quotable truth: If it renews automatically, it should be guilty until proven useful.
5) Net worth tracking: because “I feel fine” is not a metric
Net worth is where the truth lives. You can have a high income and a low net worth. That’s not success, it’s a high-performance treadmill.
FIYR tracks assets and liabilities, giving you a clearer picture than “my checking account looks okay.”
If you care about accuracy and not lying to yourself with accidental double-counting, this is worth bookmarking: FIYR net worth tracker: how to set it up for accuracy.
One-liner: Your salary is a screenshot. Your net worth is the movie.
6) Savings rate + FIRE date: the scoreboard for freedom
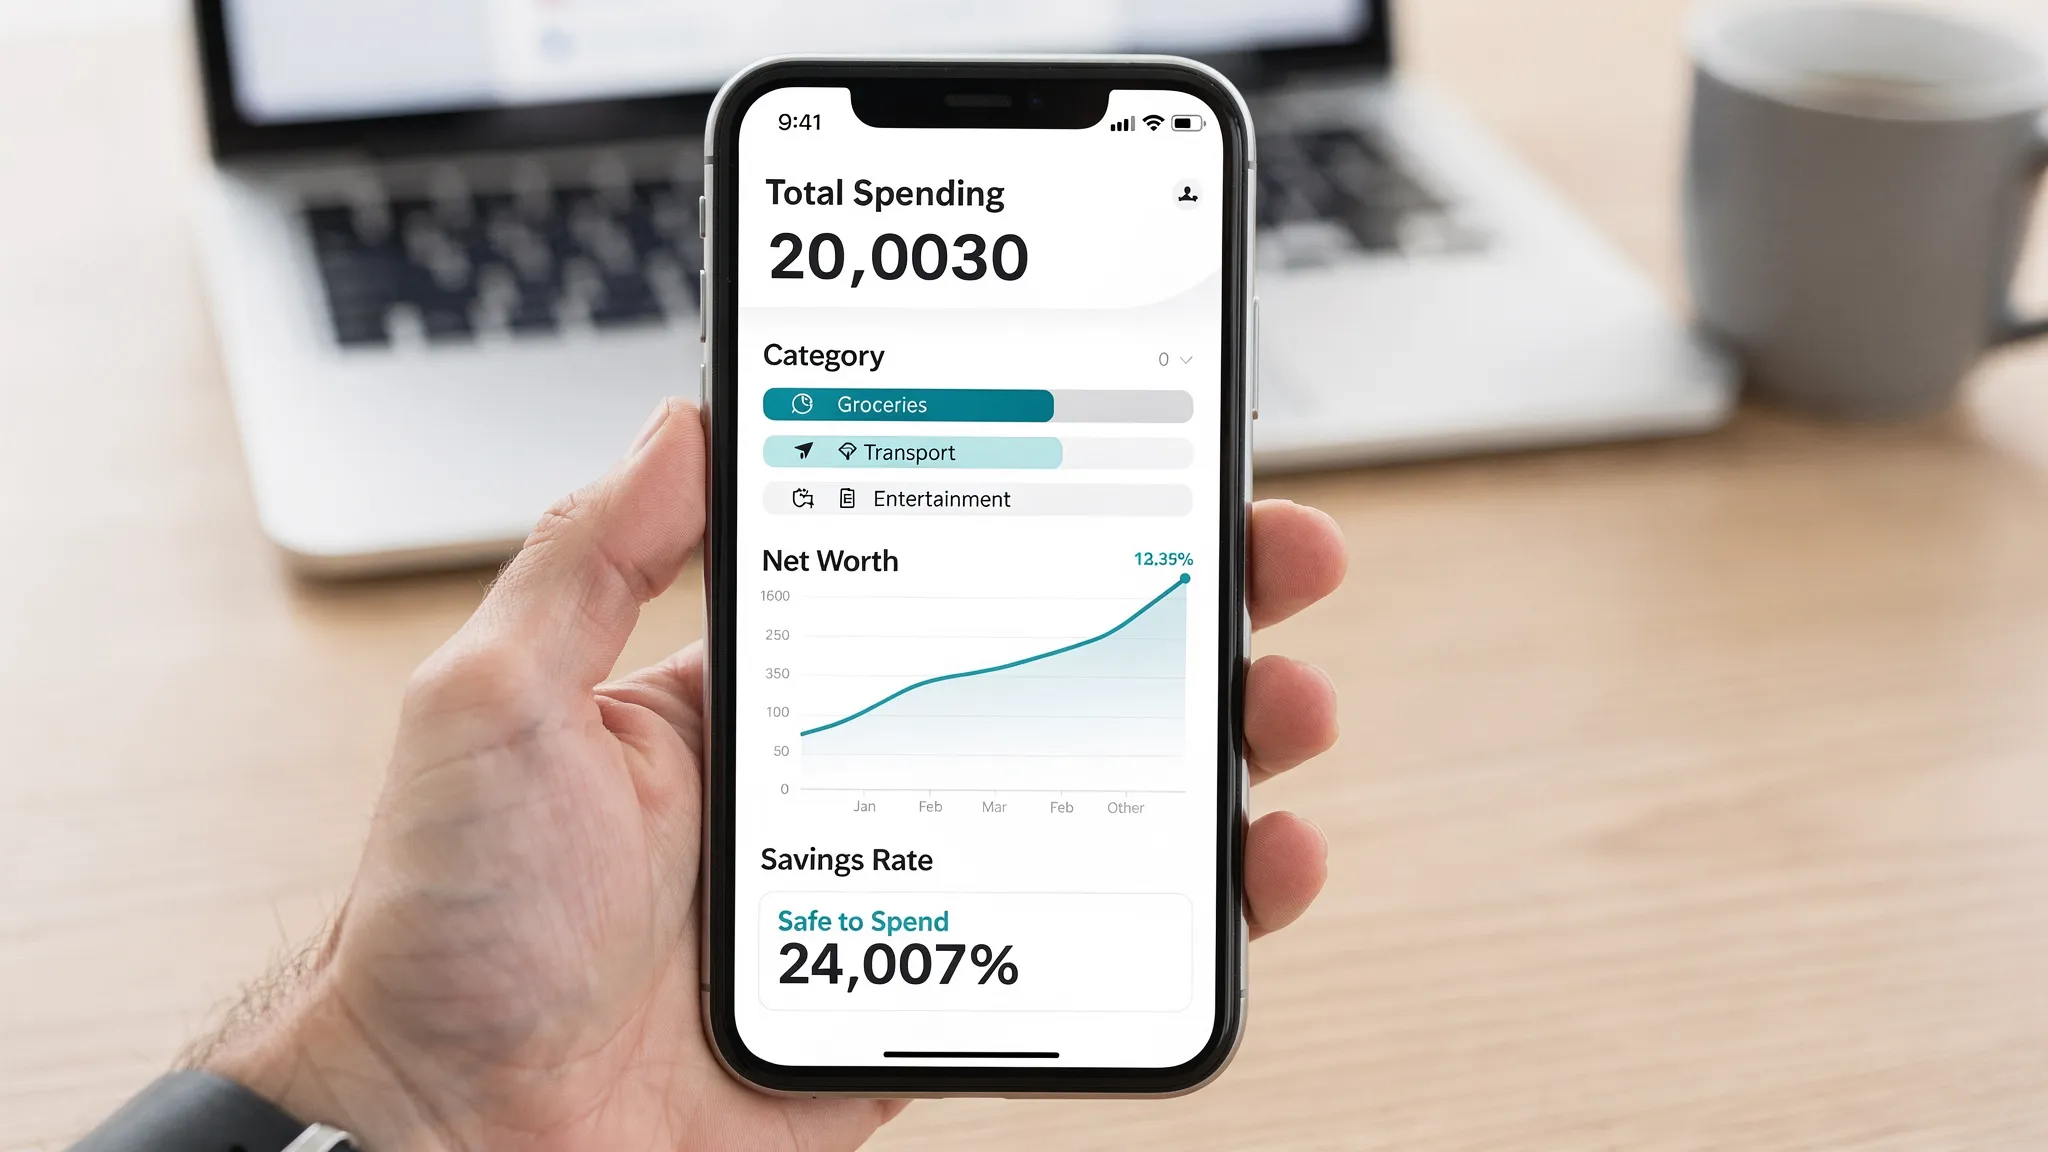
FIYR includes a savings rate calculator and a FIRE date calculator based on your real data.
This matters because FIRE isn’t “invest harder.” It’s “spend intentionally and save aggressively enough that work becomes optional.” The timeline is incredibly sensitive to what you save.
If you want the “why,” not just the number, read: Savings rate for FIRE: the fastest path to freedom.
Quotable truth: FIRE is not a personality, it’s a savings rate with receipts.
What FIYR does especially well
Clean, customizable structure without turning into a hobby
Some apps are so rigid they feel like joining a cult. Others are so flexible they feel like building your own accounting software from scratch.
FIYR lands in a useful middle: flexible where it matters (categories, rules, budgets), structured where it helps (metrics, visibility, clarity).
FIRE-friendly by design
Most budgeting apps stop at “here’s what you spent.”
FIYR nudges you toward “here’s what that means for your savings rate, net worth, and financial independence timeline.”
That’s a different product philosophy, and if you’re even mildly FIRE-curious, it’s a big deal.
“Safe to spend” and goal tracking (aka fewer financial panic spirals)
Goal tracking plus a safe-to-spend style balance is where budgeting gets practical. Not aspirational. Practical.
Because you don’t need more guilt. You need a number you can trust.
One-liner: Clarity beats discipline. Every time.
Where FIYR may not be your soulmate
No tool is perfect for everyone. FIYR is likely not the best fit if:
- You want extreme, envelope-style micromanagement and love assigning every dollar manually (you might prefer a more strict zero-based workflow)
- You hate customization and want a one-click financial life with no decisions (good luck, but I respect the dream)
Also, like any modern app that relies on data connections, your experience can depend on your institutions and syncing reliability. This is not a FIYR-only issue, it’s the entire ecosystem. If you want a reality check on how syncing breaks, this guide is worth it: Finance apps that sync with banks: the 2026 reliability guide.
FIYR vs Mint, Monarch, Copilot, Rocket Money, Quicken (quick context)
You don’t need a 47-row spreadsheet to decide. You need to match the tool to the job.
- If you miss Mint, you probably want something modern, customizable, and built for today’s subscription-heavy life. FIYR is designed for that. (More context: FIYR vs Mint: which budgeting style fits you best in 2026?)
- If you’re comparing to Monarch or Copilot, the differentiator is usually how much flexibility, automation, and FIRE-specific guidance you want.
- If you’re coming from Quicken, the win is usually speed, interface, and modern workflows like rules, cleaner categorization, and subscription visibility.
The punchline: Pick the tracker that gives you the cleanest truth with the least effort. Everything else is decoration.
The 30-minute FIYR test drive (do this, don’t “explore”)
“Exploring” a finance app is how you burn an hour and learn nothing.
Instead, run a timeboxed test. In 30 minutes, you should be able to answer: “Will this tool make my financial life clearer in a week?”
Here’s a simple FIYR test drive script:
- Connect accounts (or import what you have) and scan the last 30 to 60 days of transactions
- Create 3 to 5 custom categories that reflect your real spending (not your fantasy self)
- Add 5 basic transaction rules for your most common merchants
- Check subscriptions and flag at least one you would cancel, downgrade, or rotate
- Look at savings rate and net worth, then pick one lever to pull this week
If you want a more guided setup, this walkthrough is built for momentum: FIYR budgeting tutorial: your first week setup, step by step.
One-liner: A finance app is only “easy” if you still use it when life gets loud.
Who FIYR is best for
FIYR tends to shine for:
- Former Mint users who want a modern replacement
- People who need custom categories + transaction rules to keep data clean
- Subscription-heavy spenders who want recurring charges visible
- FIRE-minded users tracking savings rate, net worth, and a FI timeline
- Freelancers and variable-income earners who need flexible budgeting
If your life includes irregular income, kids, side hustles, or a calendar full of lumpy expenses, you don’t need a stricter tool. You need a sturdier one.
Frequently Asked Questions
Is FIYR a good Mint replacement? For many Mint refugees, yes, especially if you care about customizable categories, automation rules, subscription tracking, and FIRE-focused metrics like savings rate and FI timelines.
What makes FIYR different from a basic budgeting app? FIYR blends everyday money tracking (income, expenses, budgets) with longer-term visibility (net worth, savings rate, FIRE date) so decisions connect to outcomes.
Do I need to track every transaction manually? The point is to do less manual work over time. FIYR supports automatic transaction rules so your categories get cleaner with less effort.
Can FIYR help me reduce subscriptions? It can help you spot recurring charges and keep them visible inside your budget. Pair that with a monthly subscription audit for best results.
How often should I check a money tracker like FIYR? Weekly is the sweet spot for most people. Ten to fifteen minutes is enough to review categories, spot leaks, and reset spending guardrails.
The call: stop budgeting with vibes
If you want a money tracker that turns chaos into clarity, FIYR is worth a real test drive.
Start small: get your categories clean, automate the obvious rules, surface subscriptions, and watch your savings rate like it’s the scoreboard for your future freedom.
You don’t need more motivation. You need a system that tells the truth.
Explore more guides (and build a setup you will actually keep) at FIYR’s blog.