Budgeting for Beginners Without the Spreadsheet Meltdown
If your “budget” currently lives in a spreadsheet named Budget_FINAL_v7(2)_actually_final.xlsx, congratulations, you have built a tiny financial anxiety machine.
Most people don’t fail at budgeting because they’re bad at math. They fail because their system collapses the moment real life shows up: a surprise car repair, a birthday weekend, a “free trial” that quietly becomes a $19.99/month situationship.
And the stakes are not cute. CNBC reported that 60% of Americans are still living paycheck to paycheck, 70% are stressed about money, and only 45% have emergency savings (with 26% having under $5,000). Also, 61% carry credit card debt. That’s not “oops.” That’s structural pressure. Here’s the source: CNBC’s paycheck-to-paycheck snapshot.
So if budgeting feels hard, you’re not broken. Your tools are just stuck in 2009.
The beginner budgeting trap: spreadsheets don’t bend
Meet Jordan.
Jordan downloads a budgeting template. It has colors. It has formulas. It has confidence.
Week 1: Jordan tracks every transaction like a caffeinated accountant.
Week 2: One dinner out gets split across three cards, a Venmo reimbursement, and a “we’ll settle up later.” The spreadsheet starts whispering threats.
Week 3: Jordan misses a few entries. Now the budget is lying. Jordan knows it’s lying. And when your budget lies, your brain does what it always does when confronted with useless information.
It quits.
Spreadsheets aren’t evil. They’re just fragile. Budgeting for beginners needs something resilient, because beginners need feedback loops, not homework.
Quotable truth: A budget that requires perfect behavior is a fantasy novel.
The real goal: control, not perfection
Beginner budgeting advice on the internet is obsessed with “getting it right.” Here’s the better goal:
Make your money decisions easier next week than they were last week.
That means:
- Seeing what you actually spend (not what you wish you spent)
- Setting a few guardrails (not 47 categories)
- Building a rhythm you can repeat when you’re busy, tired, or mildly feral
This is why modern tracking beats manual entry for most people. The best system doesn’t ask you to be a monk. It asks you to be consistent.
Your Minimum Viable Budget (MVB): 3 buckets, 2 rules, 1 weekly check-in
Budgeting for beginners works best when you reduce decisions. The Minimum Viable Budget is the smallest setup that still changes your behavior.
Step 1: Pick your “win condition”
A win condition is the one thing you want your budget to do right now.
Examples:
- Stop overdrafting
- Pay off credit cards without feeling deprived
- Build a $1,000 starter emergency fund
- Get spending under control so you can start investing
If you try to do everything, you’ll do nothing, but with prettier charts.
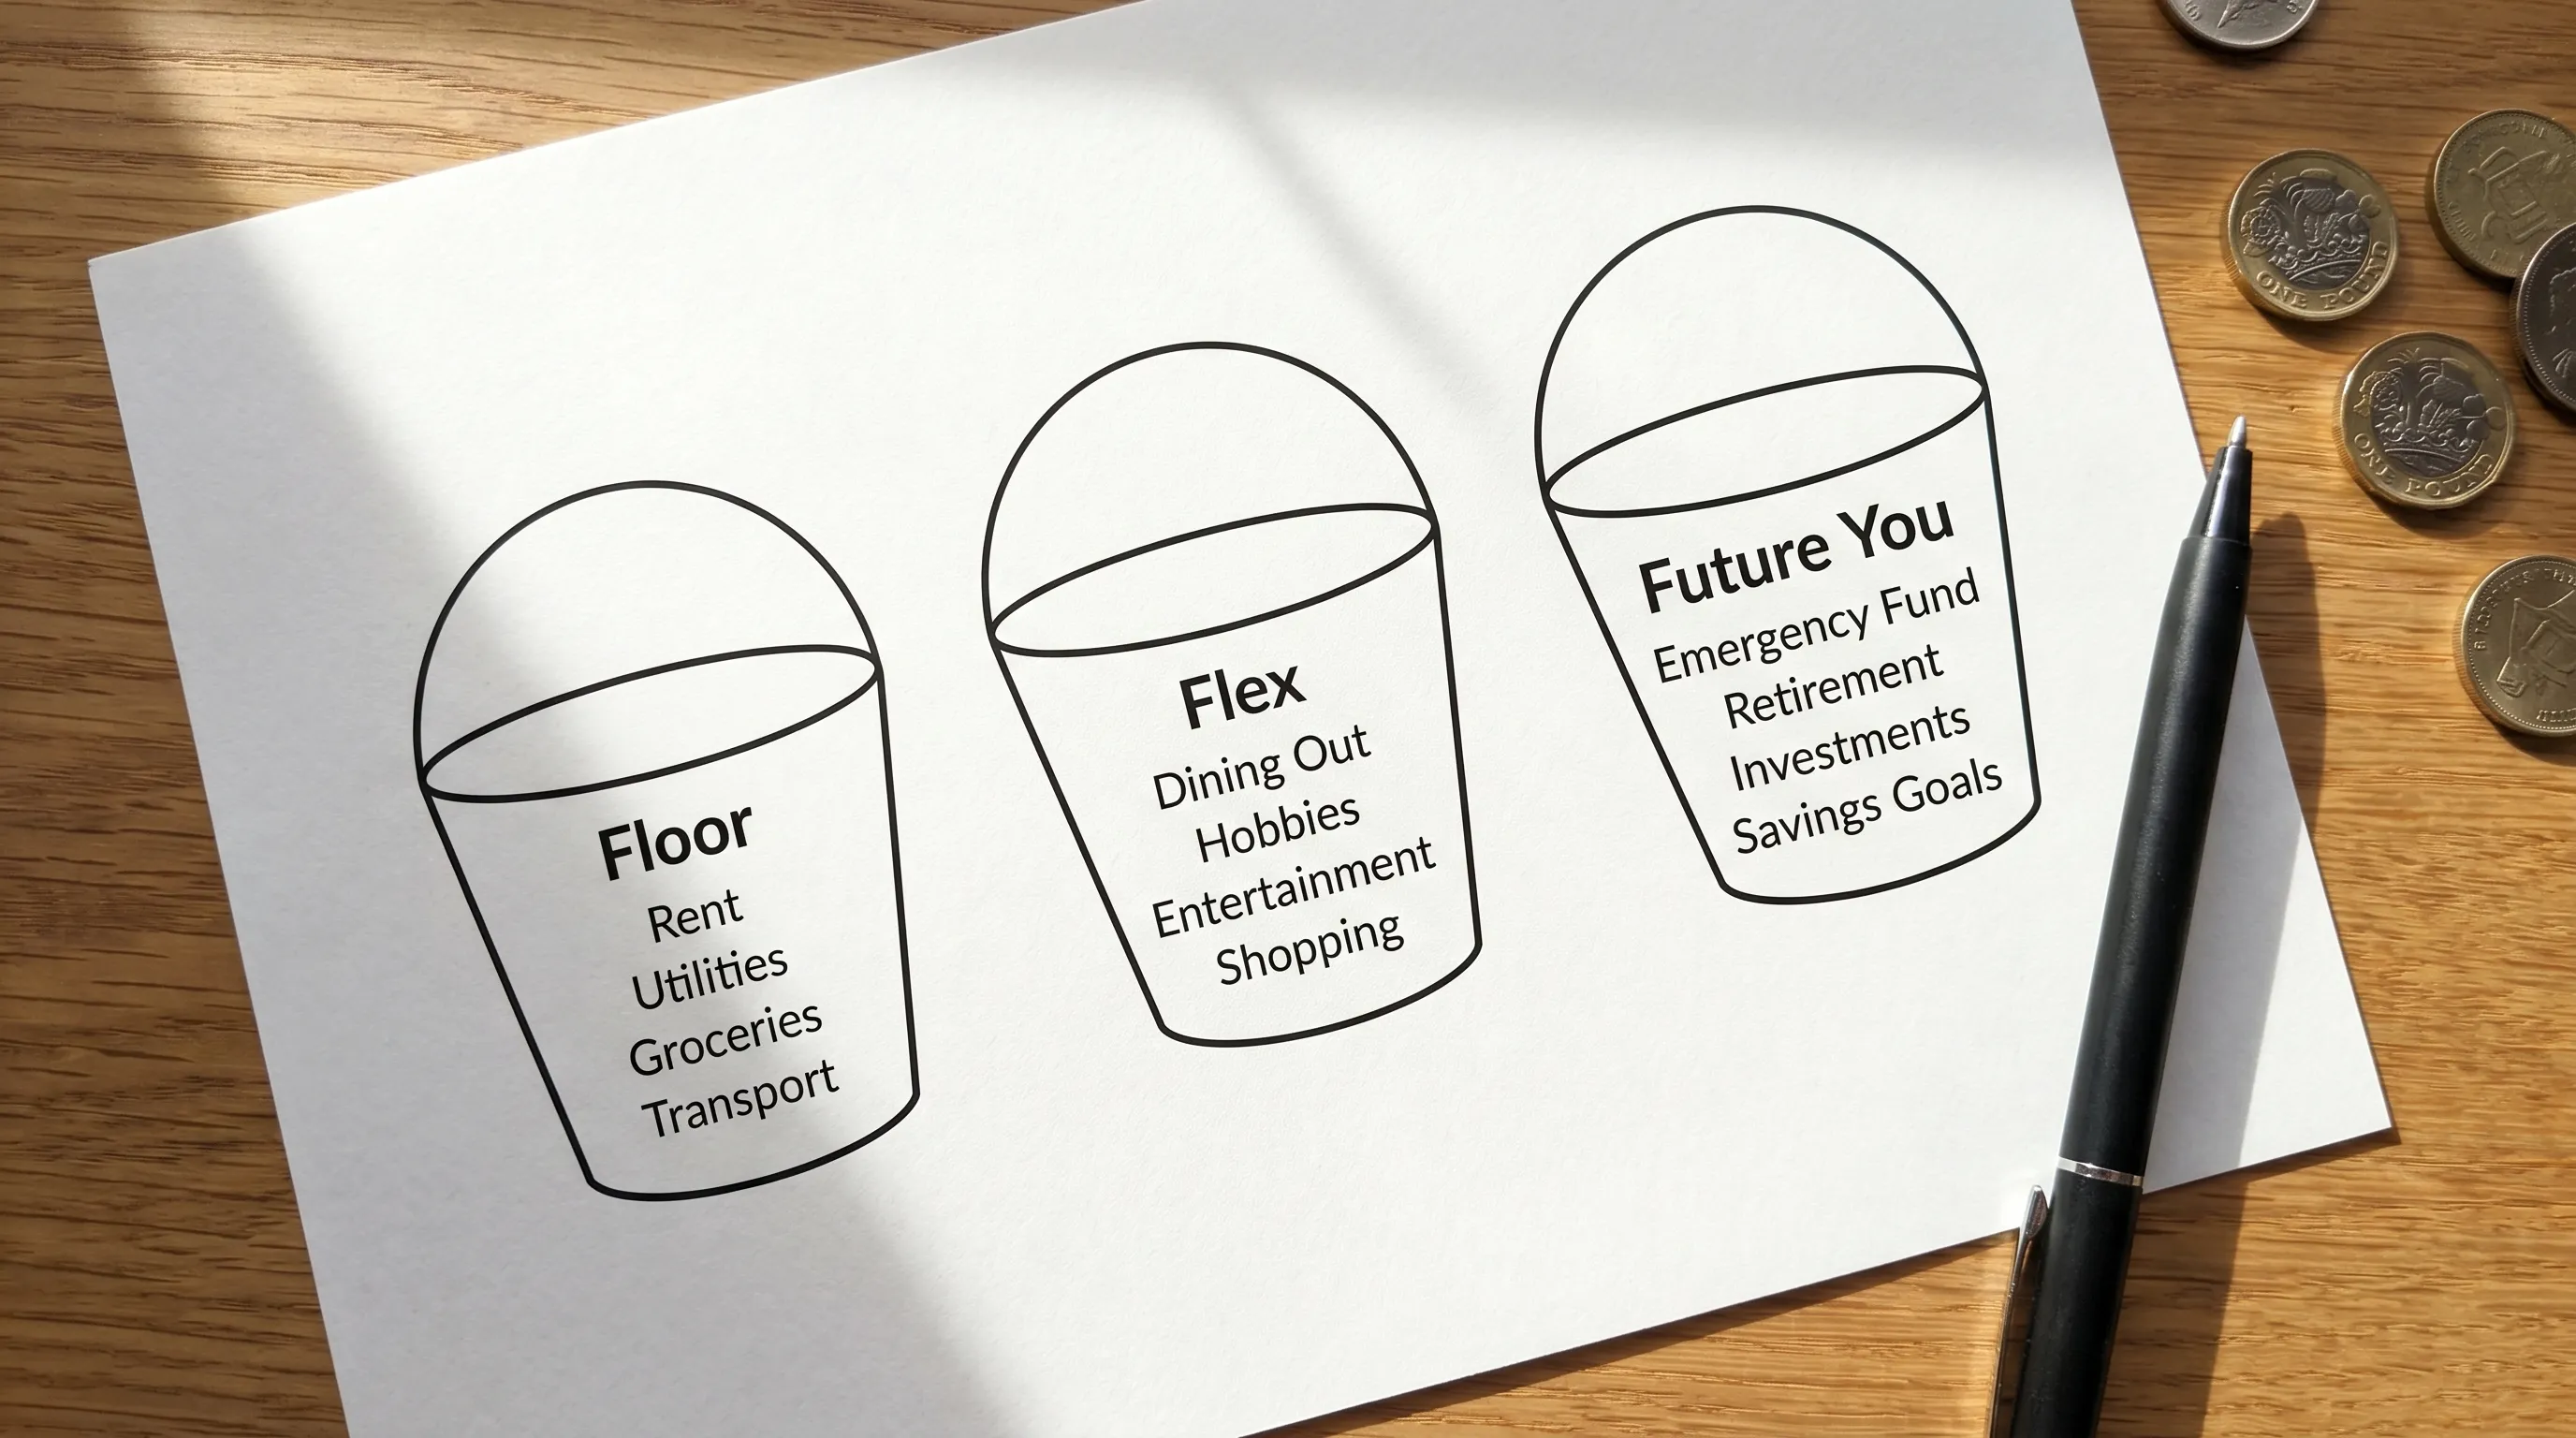
Step 2: Use the 3-bucket structure (so your budget can breathe)
You do not need a category for “paper towels” and another for “other paper towels.” You need buckets that map to decisions.
Here’s the simple structure:
| Bucket | What it covers | What success looks like |
|---|---|---|
| Floor | Non-negotiables you must pay to keep life running | Bills paid on time, no panic |
| Flex | Day-to-day spending that can drift | You stay within a cap most weeks |
| Future You | Savings, debt payoff, investing, sinking funds | You’re paying yourself first |
Examples by bucket:
- Floor: rent/mortgage, utilities, insurance, minimum debt payments, childcare
- Flex: groceries, dining, coffee, fun, gas, Amazon chaos
- Future You: extra debt payments, emergency fund, retirement contributions, “true expenses” like car repairs
Quotable truth: Buckets beat categories because buckets beat excuses.
Step 3: Set just two rules (yes, only two)
Rules are where budgeting becomes real.
Rule #1: Pay Future You first.
Even if it’s small. Even if it’s $25/week. The point is to create the habit loop.
Rule #2: Cap your top two “leak categories.”
Not everything. Just the two categories that consistently jump you in a dark alley.
Common leak categories:
- Dining and delivery
- Shopping (especially “one-click therapy”)
- Convenience spending (parking, fees, random snacks, small impulse buys)
- Subscriptions
Pick two, set caps, move on.
“Okay, but how do I pick numbers without guessing?”
Great question. Here’s the part nobody talks about: your first budget isn’t a plan, it’s a hypothesis.
So instead of guessing, run a quick baseline.
The 20-minute baseline (no spreadsheet meltdown required)
Do this with the last 30 to 60 days of transactions:
- Total your take-home income for the month
- Total your Floor costs
- See what’s left for Flex + Future You
If Floor eats everything, that’s not a “budgeting problem.” That’s a fixed-cost problem (housing, car, debt). Different battle.
If there’s room, you now have a starting point for caps.
Here’s a clean way to think about allocation as a beginner:
| If your situation is… | Floor target | Flex target | Future You target |
|---|---|---|---|
| Stable, low debt | ~50% to 65% | ~20% to 35% | ~10% to 25% |
| High cost of living | ~65% to 75% | ~15% to 25% | ~5% to 15% |
| Debt payoff season | ~55% to 70% | ~15% to 25% | ~10% to 30% |
These are ranges, not commandments. The only “correct” budget is the one you can run for 90 days.
Quotable truth: A realistic budget beats an optimal budget the way cardio beats intentions.
The hidden villain: financial admin fatigue
Budgeting isn’t hard because the math is hard.
Budgeting is hard because modern money is a never-ending stream of tiny decisions:
- Tap-to-pay
- One-click checkout
- Subscriptions you forgot existed
- Buy now, pay later disguised as “self care”
The fix is not more willpower. The fix is less manual work.
That’s why tools that automatically track transactions, categorize spending, and surface subscriptions tend to win long-term. They reduce the tax your life pays for being busy.
How to avoid the top 6 beginner budgeting meltdowns
Here are the common failure modes, and the antidotes.
| Meltdown | What it looks like | The fix |
|---|---|---|
| Too many categories | 37 categories, none are useful | Shrink to 8 to 12 decision categories |
| “Random” overspending | You’re always surprised by totals | Add caps to two leak categories |
| Subscriptions creep | You “only have a few” but pay $300/month | Monthly subscription audit, set a subscription cap |
| True expenses ambush | Annual bills explode your month | Create sinking funds (monthly-ize the pain) |
| Messy transactions | Transfers counted as spending, duplicates | Clean rules for transfers and recurring items |
| No review rhythm | You budget once, then ghost it | Weekly 10 to 15 minute check-in |
Budgeting for beginners isn’t about discipline. It’s about designing a system that doesn’t hate you.
The beginner-friendly weekly routine (12 minutes, tops)
You don’t need daily tracking. You need a weekly glance that keeps you honest.
The 12-minute Money Check-In
- Check your safe-to-spend number (what’s left after Floor and your planned Future You moves)
- Scan the two leak categories, are you on track or drifting?
- Approve or fix any miscategorized transactions
- Look for any new subscriptions or recurring charges
- Decide one action for the week (cancel, cap, renegotiate, or automate)
That’s it. No incense. No spreadsheets. No financial guilt spiral.
Quotable truth: Budgets don’t fail on big decisions. They fail on ignored Tuesdays.
“But I have irregular income.” Cool, you need two budgets.
If your income varies (freelancing, commission, gig work), beginners often make one mistake: they budget like they’re paid the same every month.
Instead:
- Build a Survival budget (Floor + minimum Flex)
- Build a Thrive budget (your ideal month)
Then base your monthly plan on a conservative income floor.
If you’re a freelancer, creator, or small business owner, you can also take this one step further: track personal spending separately from business cash flow so you don’t accidentally turn “a good revenue month” into “a mysterious personal spending month.”
And if marketing spend is part of your world, budget it like a grown-up. “Vibes” is not a line item. If you want help scaling leads and revenue with automation (without duct-taping 12 tools together), you might look at an AI-powered digital marketing agency like Lotiva.
Where FIYR fits (without the hard sell)
Spreadsheets melt down because they require manual upkeep. A modern money tracker reduces upkeep by making the truth easy to see.
FIYR is built for exactly the stuff that trips up budgeting for beginners:
- Spending tracking that shows where your money actually went
- Flexible budgeting so one weird week doesn’t ruin your month
- Custom categories and category groups so “Amazon” stops being a black hole
- Automatic transaction rules so recurring stuff gets categorized without your involvement
- Subscription tracking because your money should not be quietly dating 14 apps
- Safe-to-spend and goal tracking so your day-to-day spending doesn’t sabotage Future You
- Savings rate and FIRE insights if you want your budget to do more than just “not be broke”
If you want the simplest on-ramp, start with the three buckets, then automate the recurring stuff. You can also steal ideas from FIYR’s walkthrough on a simple budgeting setup and (when you’re ready) upgrade your data quality with custom categories that actually mean something.
Quotable truth: A budget is just a story your data can prove.
Frequently Asked Questions
What’s the best budgeting method for beginners? The best method is the one you’ll still do in 90 days. For most people, a simple 3-bucket budget (Floor, Flex, Future You) plus a weekly check-in wins because it’s resilient.
Do I need a spreadsheet to budget? No. Spreadsheets are fine for planning scenarios, but daily money management is easier when transactions and categories update automatically. Less manual work means more consistency.
How many categories should a beginner budget have? Start with 8 to 12 decision-focused categories (plus your three big buckets). Too many categories creates admin fatigue and makes you quit.
What if I overspend one week? Don’t restart the whole budget. Use a flexible system: tighten the leak categories for the next week, pause one optional purchase, and move on. The goal is correction, not punishment.
How much time should budgeting take each week? About 10 to 15 minutes. If it takes an hour, the system is too complicated or too manual.
Ready to budget without the chaos?
If you’re done babysitting a spreadsheet and ready for a system that survives real life, build your Minimum Viable Budget and let automation do the boring parts.
FIYR helps you track spending, set flexible budgets, spot subscriptions, and see a clean safe-to-spend number, without turning your Sunday into an accounting internship. Start simple, get consistent, then get ambitious. Your future self will be annoyingly grateful.
Explore FIYR and the rest of the playbooks at FIYR’s blog.