Best Financial Independence Tools: Track, Plan, Retire Sooner
If you’re looking for the best financial independence tools, you’re probably expecting a shiny list of apps that promise “retire by 40” with the confidence of a crypto bro in 2021.
Here’s the uncomfortable truth: most people don’t fail at FIRE because they picked the wrong ETF. They fail because their numbers are vibes.
And vibes do not compound.
A reality check: CNBC reported that 60% of Americans are still living paycheck to paycheck, with 70% stressed about finances, and 3 in 5 carrying credit card debt (CNBC). That’s not a “buy VTI” problem. That’s a “your system is leaking” problem.
So let’s build the tool stack that actually gets you to financial independence faster, with fewer spreadsheets, fewer surprises, and fewer “wait, I’m still paying for that?” moments.
The only 5 jobs your financial independence tools need to do
Forget the app hype. Tools are only useful if they do a job.
The best financial independence tools handle five jobs:
- Tell the truth (income, spending, net worth, debt)
- Create constraints (budgets that survive real life)
- Automate the boring (rules, recurring bills, subscriptions)
- Project the future (savings rate, FI number, FIRE date)
- Turn insight into action (safe-to-spend, goals, debt payoff)
Here’s what that looks like in plain English.
| Job to be done | What it prevents | Tool type that solves it | What to demand (non-negotiable) |
|---|---|---|---|
| Tell the truth | “I think I save money” delusion | Money tracker + categorization | Clean categories, rules, review workflow |
| Create constraints | Lifestyle creep in a trench coat | Budgeting system | Flexible caps, rollover/buffers, “safe-to-spend” |
| Automate the boring | Falling off after Week 2 | Automation + subscriptions | Transaction rules, recurring detection, alerts |
| Project the future | Working forever by accident | FIRE calculators + modeling | Uses real spending data, scenario toggles |
| Turn insight into action | Knowing, but not doing | Goal + debt + habit tools | Goal tracking, payoff planning, routines |
If your current setup doesn’t do those jobs, it’s not a system. It’s a dashboard you occasionally feel guilty about.
Tool #1: A money tracker that becomes your “source of truth”
Meet Sarah.
Sarah makes good money, has a 401(k), and still feels broke. She assumes it’s inflation, greedy corporations, and “society.” (All possible.)
Then she links her accounts to a tracker and discovers:
- She’s spending $640/month on “food,” which is mostly delivery fees and sadness
- She has three subscriptions for workouts she is not doing
- Her “misc” category is basically a financial junk drawer
This is the first win of the best financial independence tools: they end the guessing game.
What to look for in a money tracker (especially if you’re ex-Mint):
- Accurate income and expense tracking (with an easy way to review anomalies)
- Custom categories and category groups (because “Shopping” is not a plan)
- Automatic transaction rules (so you’re not manually tagging Target like it’s 2009)
- Subscription tracking (recurring charges should not be stealth)
- Net worth tracking (assets + liabilities, no fantasy math)
- Savings rate tracking (the actual speedometer of FIRE)
FIYR fits here naturally because it’s built as a modern alternative to Mint, Monarch Money, Copilot, Rocket Money, and Quicken, with a FIRE-first emphasis. It’s not just tracking what happened, it’s helping you connect what happened to when you can stop working.
Quotable truth: If your tracker can’t tell you where the money went, it can’t tell you when you can leave.
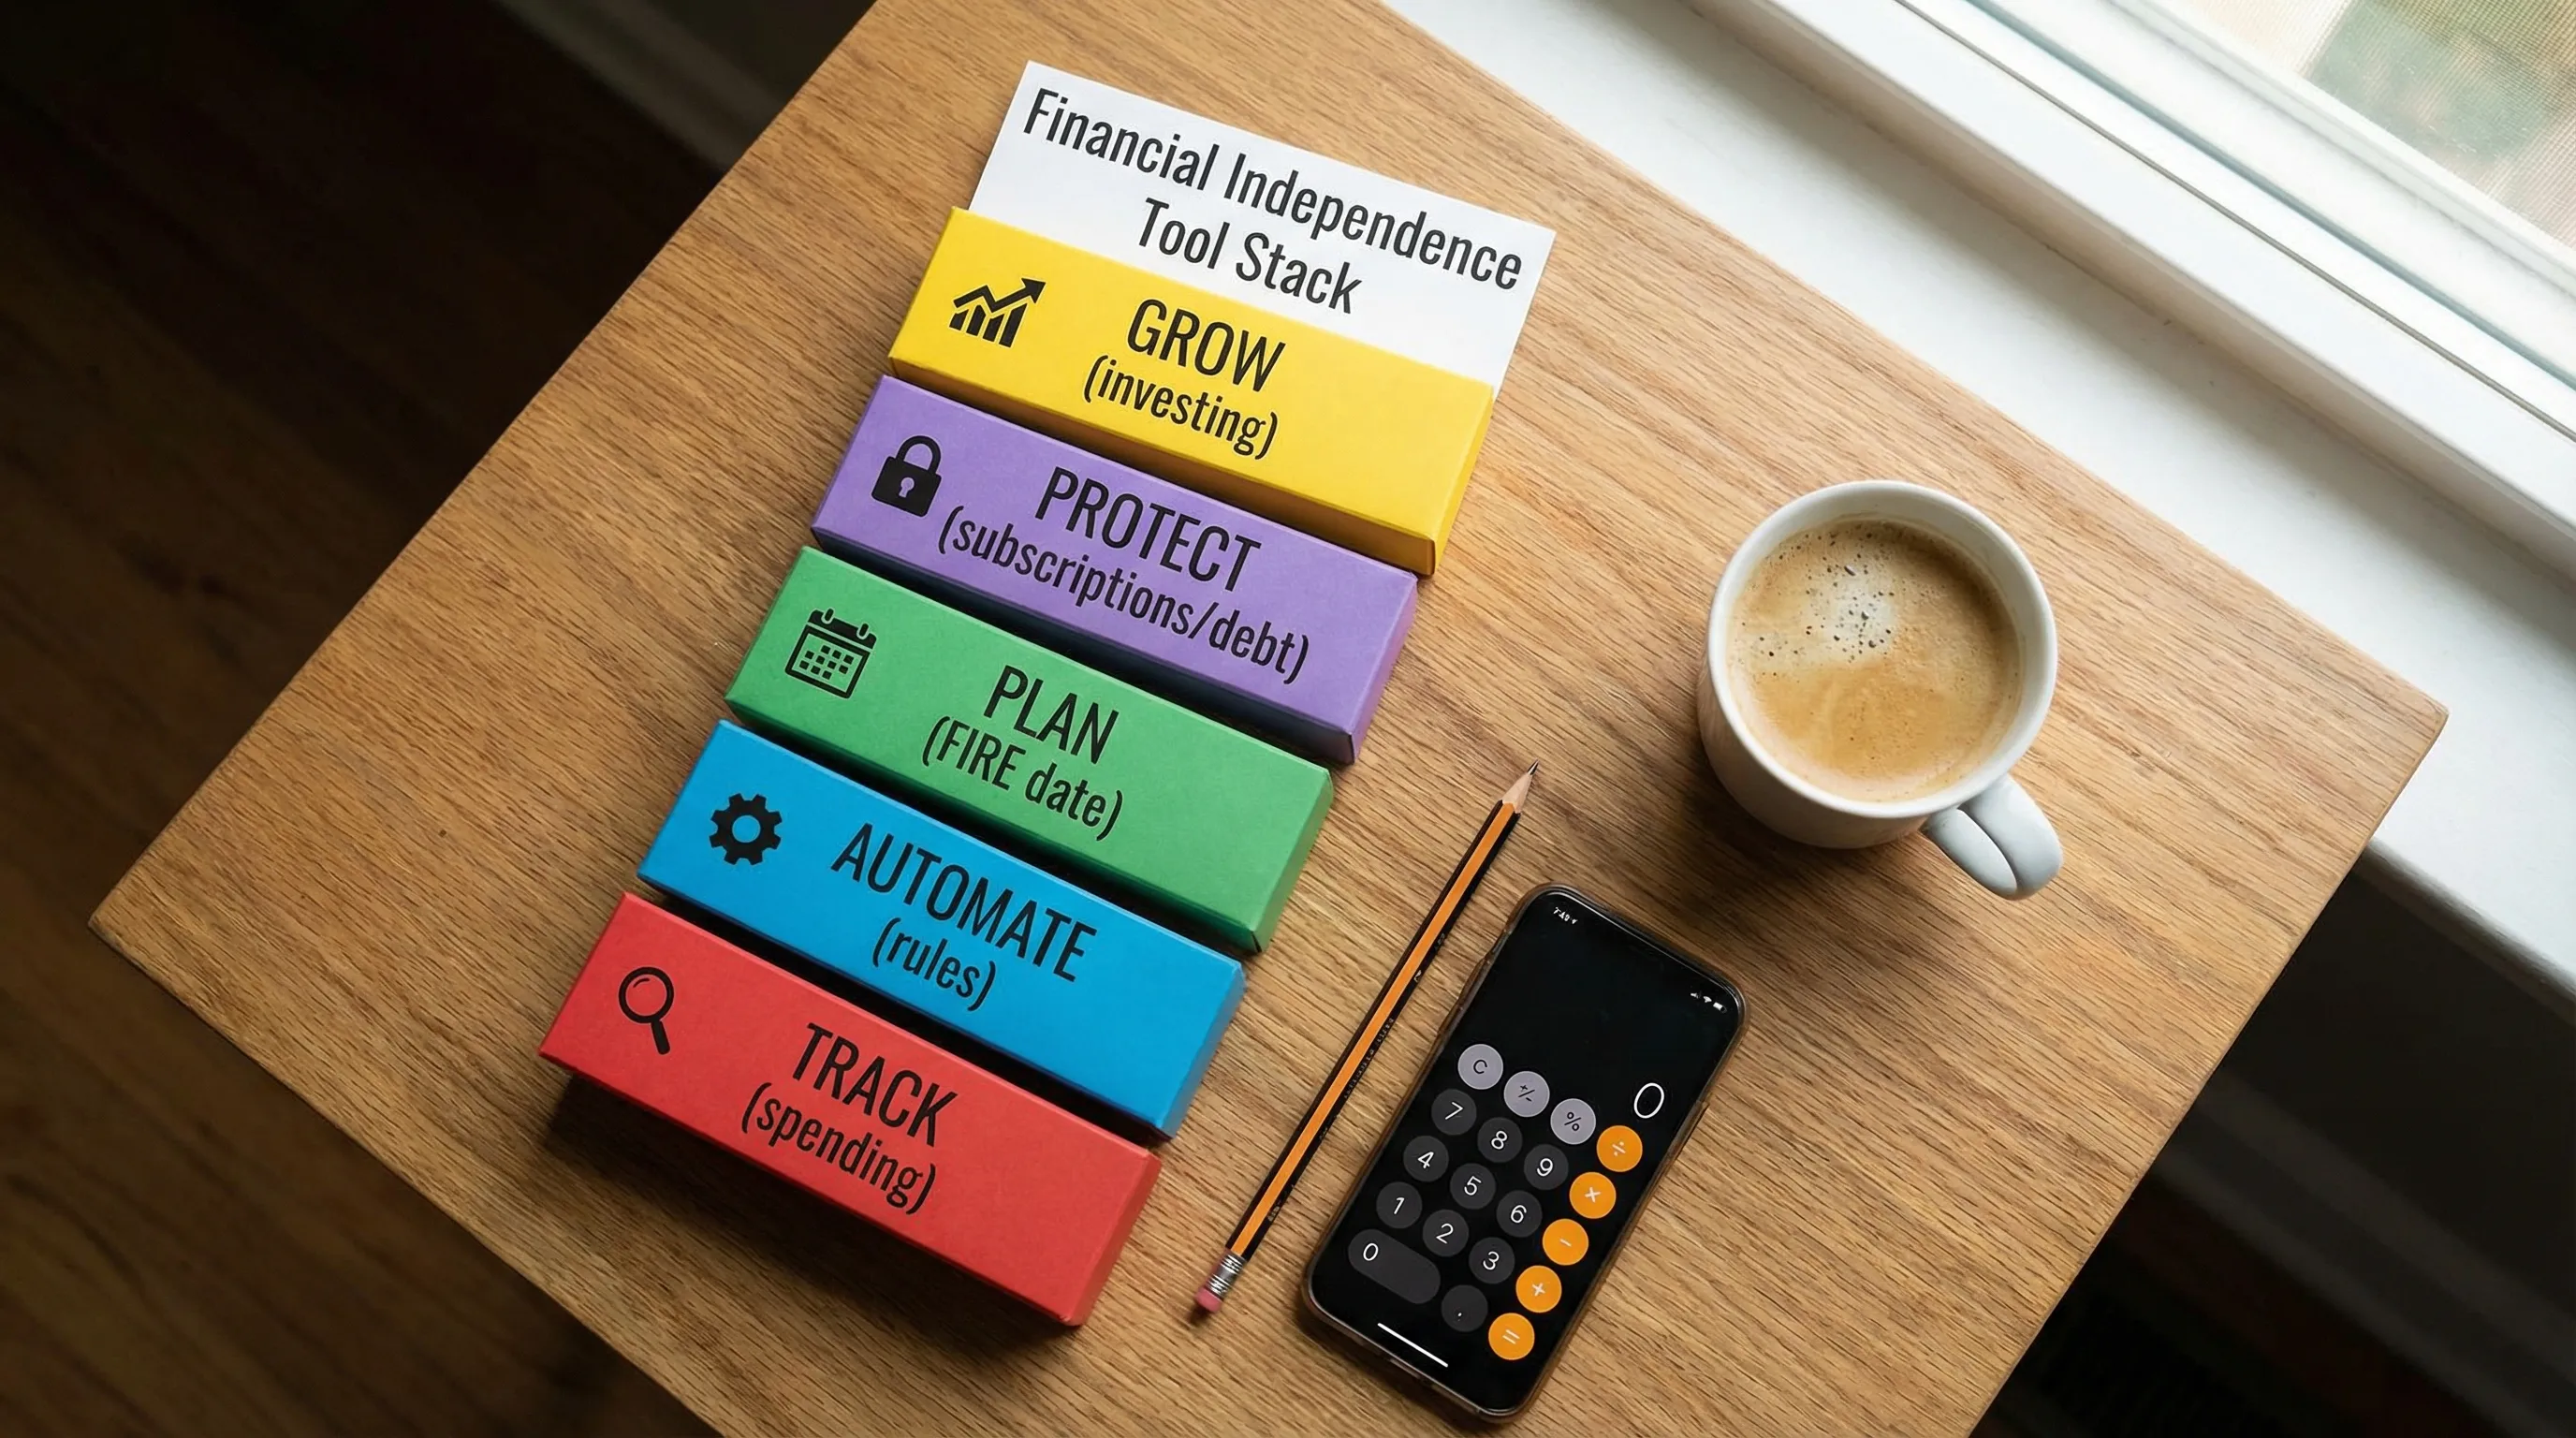
Tool #2: Budgeting that bends instead of breaking
Most budgets fail because they’re designed for a fictional person.
You know the one:
- Cooks every meal
- Never gets invited to weddings
- Doesn’t have a car that randomly decides it needs $900 of “maintenance”
Real budgeting for FIRE needs flex.
Your tool should support things like:
- Dynamic budgets (caps that adjust, rollover categories, buffers)
- Goal-based budgeting (so “saving” isn’t a vague good intention)
- Safe-to-spend (what’s actually available after bills and goals)
This is where FIYR’s budgeting approach shines in practice: you can track spending in a way that keeps budgets realistic, while still protecting your savings rate.
One-liner to steal: A budget that can’t survive Friday night is not a budget, it’s fan fiction.
Tool #3: Savings rate tracking (your FIRE speedometer)
People obsess over returns because it’s sexy. Savings rate is not sexy. Savings rate is effective.
Savings rate answers one question: How fast are you buying your freedom?
A good system calculates it consistently and makes it easy to improve.
If you want the deep dive, FIYR has strong supporting guides like Savings Rate for FIRE: The Fastest Path to Freedom, but here’s the operational takeaway:
- Your savings rate is a monthly performance metric
- It’s influenced more by spending control + income growth than market wizardry
- It’s the cleanest lever for pulling your FIRE date closer
Quotable truth: You don’t need a perfect portfolio, you need a ruthless savings rate.
Tool #4: Net worth tracking (because income is not wealth)
Income is a flow. Net worth is the scoreboard.
If you don’t track net worth, you miss things like:
- Debt quietly growing while your paycheck looks “fine”
- Cash buffers shrinking while spending stays flat
- Progress toward FIRE that’s hidden because you’re only watching balances, not the full picture
What “good” looks like in a net worth tool:
- Tracks assets and liabilities (yes, include the boring debts)
- Lets you add items that aren’t perfectly synced (manual assets still count)
- Doesn’t double-count transfers (the classic tracker lie)
- Makes it easy to do a monthly reconcile ritual
FIYR supports net worth tracking across assets and liabilities, which matters because FIRE math is basically net worth plus behavior, then time.
One-liner: Your salary can look rich while your net worth looks like a crime scene.
Tool #5: A FIRE calculator that uses real data, not wishful thinking
Most FIRE calculators are like fortune cookies with spreadsheets.
The best financial independence tools do something more honest: they build projections from your actual spending, savings rate, and net worth.
Here’s what to demand:
- Ability to model different savings rates (and see the date change)
- Clear assumptions (withdrawal rate, returns, inflation)
- Sensitivity toggles (what happens if spending goes up, or income drops)
If you want a practical walk-through on the inputs that move the needle, FIYR’s FIRE Calculator 2026 guide is a solid companion.
Quotable truth: The best FIRE calculator doesn’t motivate you, it confronts you.
Tool #6: Subscription tracking (death by a thousand $14.99s)
Subscriptions are the modern tax for being alive.
Streaming, apps, “premium,” memberships, meal kits, cloud storage, productivity tools you use twice a year, it adds up because it’s designed to be invisible.
The right tool should:
- Detect recurring charges
- Show total monthly subscription spend
- Make it easy to label and categorize recurring charges correctly
FIYR includes subscription tracking as part of the core system, which matters because recurring spend is one of the easiest, least painful ways to raise savings rate.
One-liner: Subscriptions are frictionless spending with a monthly billing cycle and a straight face.
Tool #7: Debt payoff planning (because interest is anti-FIRE)
Debt is the opposite of compounding. It’s compounding, but for the bank.
If you’re carrying high-interest debt, your “investment strategy” is mostly just donating returns to Visa.
A good payoff tool (or module) should help you:
- Track balances, APRs, minimums, and due dates
- Choose a payoff strategy (avalanche or snowball)
- See the payoff timeline change when you add extra payments
FIYR already supports liability tracking, which makes debt visible and measurable, and visibility is the first step to murderously efficient payoff.
Quotable truth: High-interest debt is a FIRE date assassin.
Tool #8: A simple scenario model (spreadsheets are fine, until they become your personality)
Spreadsheets are powerful. They’re also fragile.
They break when:
- Your categories change
- Your bank description changes
- You miss a month because you had a life
My favorite setup for most people pursuing FIRE:
- Use a tracker (like FIYR) for ongoing truth and automation
- Use a simple spreadsheet for big what-if scenarios (home purchase, sabbatical, daycare, business launch)
The tool is less important than the rule:
Keep daily tracking automated, keep scenario planning deliberate.
One-liner: Spreadsheets are great servants and terrible bosses.
Bonus: If you’re a business owner, you may need “grown-up” finance tools
If you’re self-employed or running a small company, your money stack can get messy fast: business subscriptions, contractor payments, reimbursements, inventory, tax estimates, multiple accounts, plus personal FIRE goals.
At some point, “personal finance app + good intentions” stops being enough.
If you’re in the mid-market world and need to connect financial systems, automate workflows, or tighten operational reporting, a resource like AI & NetSuite consulting can be worth exploring. That’s not personal budgeting, it’s operational leverage, and leverage is the business equivalent of a 50% savings rate.
Quotable truth: When your finances become a system, your tools need to level up from “budgeting” to “operations.”
A dead-simple framework to choose the best financial independence tools
Instead of reading 43 reviews and ending up more confused, score tools on what actually matters for FIRE.
| Criteria | What it means | Why FIRE people should care |
|---|---|---|
| Accuracy | Clean imports, fewer duplicates, clear reconciliation | Bad data makes bad decisions confidently |
| Automation | Rules, recurring detection, reduced manual work | Consistency beats motivation |
| Customization | Categories, labels, flexible budgets | Your life is weird, your tool should handle it |
| FIRE metrics | Savings rate, net worth trends, projections | You’re tracking freedom, not just spending |
| Actionability | Safe-to-spend, goals, insights that change behavior | Awareness is useless without decisions |
| Portability | Export options, clean history | You should be able to leave if needed |
Here’s the part nobody talks about: the “best” tool is the one you still use when life gets chaotic. When the baby’s sick, when work explodes, when you travel, when you’re just tired. That’s the real test.
The 7-day setup sprint (so your tools start paying rent immediately)
You don’t need a 12-hour “finance weekend.” You need a fast setup that creates momentum.
Do this over a week:
- Day 1: Connect accounts and set a “Needs Review” holding category. Your first goal is clean data, not perfection.
- Day 2: Create decision categories. Replace vague buckets like “Shopping” with categories that tell you what to do.
- Day 3: Add rules for your top merchants. Groceries, gas, Amazon, utilities, rent, childcare, the usual suspects.
- Day 4: Identify subscriptions and tag them cleanly. You can’t cut what you can’t see.
- Day 5: Set one or two budget caps that actually matter. Restaurants, convenience spending, impulse shopping, pick your villain.
- Day 6: Turn on goals and define your “Future You” targets. Emergency fund, debt payoff, investing, sinking funds.
- Day 7: Run your first 15-minute weekly money check-in. This is where systems are born.
FIYR makes this easier because it combines tracking, budgets, rules, subscription visibility, net worth, and FIRE projections in one place. Less duct tape, more signal.
One-liner: A tool that’s not set up is just expensive optimism.
The weekly ritual that turns tools into early retirement
Tools don’t create financial independence. Habits do.
Use this weekly script (15 minutes, no drama):
- Review any uncategorized transactions
- Check your top 2 problem categories vs cap
- Scan subscriptions for anything suspicious
- Look at savings rate (trend, not perfection)
- Pick one action for the week (cancel, cap, automate, negotiate)
Do that for three months and you’ll have something most people never get: control that doesn’t rely on willpower.
Final punchline: Financial independence isn’t a dream. It’s a spreadsheet that tells the truth, a budget that survives real life, and a system you actually repeat.
Because the goal isn’t to be good at money.
The goal is to make money boring enough that you can go live your life.